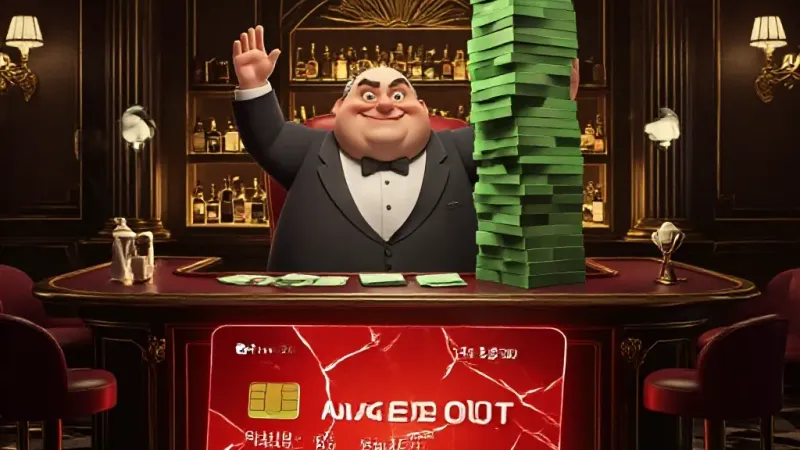
WASHINGTON D.C. — The United States Treasury officially announced today that the nation’s credit card limit has been reached, prompting a collective shrug from Capitol Hill. Sources close to the situation report the card was maxed out sometime yesterday afternoon during a record-setting spike in 10-year bond yields, which analysts confirmed was “mostly just math, probably.” The milestone, which deepened worries that rising borrowing costs will squeeze households and swell the cost of carrying the national debt, was greeted by federal officials with a casual indifference typically reserved for a forgotten streaming subscription or a slightly overdue library book.
Treasury Secretary Janet Yellen, speaking from a podium adorned with a hastily drawn "I'm With The Band" sticker, dismissed concerns. “Look, every household maxes out their credit card sometimes. It’s a sign of economic dynamism, really,” Yellen explained, nervously tapping her foot. “It just means we’re really, really good at buying things. Plus, we’re a country. We’re too big to fail. They can’t repossess the Statue of Liberty, right? They wouldn’t dare.” She added that the administration was confident they could simply apply for a new card, possibly one with a lower introductory APR, or explore a balance transfer to a slightly smaller, more desperate nation.
Congressional leaders, meanwhile, were reportedly huddled in a closed-door session debating the optimal font for next year’s budget proposal. When asked about the credit card situation, Senate Majority Leader Chuck Schumer paused, adjusted his glasses, and stated, “The American people want action, and we are acting. We’re exploring innovative new payment strategies, like asking nicely for an extension, or perhaps finding a rich relative. Maybe we can get a points bonus?” He then added, “Also, can someone put another round of drinks on the national tab? It’s been a long day of not fixing anything.”
Adding to the fiscal merriment, a source within the Treasury Department, speaking anonymously while shredding a pile of unopened bills, revealed the U.S. credit score had officially plummeted to “Needs Improvement,” just above “Actively Dodging Calls.” The source confirmed that the national mailbox was now filled exclusively with offers for subprime auto loans and debt consolidation schemes, all addressed to "Occupant."
Economist Dr. Reginald Sterling, head of the Institute for Perpetual Growth and Infinite Leveraging, praised the development. "This isn't a debt problem; it's a confidence problem... specifically, confidence that anyone will ever actually call this bluff," Sterling clarified. "By demonstrating an unparalleled commitment to unsustainable borrowing, the U.S. is signaling to global markets that we are utterly unafraid of consequences. That's financial bravado, baby. Plus, defaulting is just a fancy word for 'negotiating a better deal,' and we're *very* good negotiators."
The Treasury Department confirmed that all future interest payments will now be automatically deferred to the “Next Generation Account,” an untouchable fund managed by yet-to-be-born taxpayers, because what are they going to do, sue?