
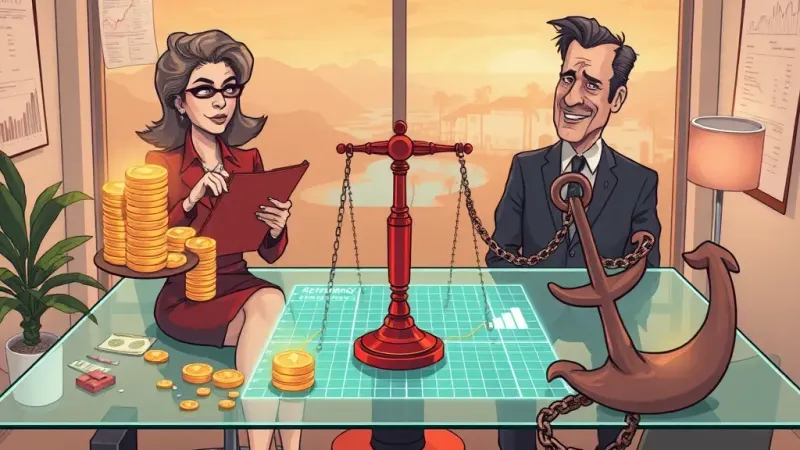
Des Moines, IA—Weighing the cold calculus of matrimonial ROI against the grim reality of a fixed-income future, local 42-year-old project manager Brenda Miller confirmed Tuesday she is currently running financial models to determine if her husband of twelve years is worth a 34 percent reduction in her monthly pension.
The analysis, which involves complex actuarial spreadsheets comparing David Miller’s projected caloric intake against current bond yields, is part of a growing retirement planning trend where Americans treat their immediate family members as expensive, high-maintenance subscription services that can be canceled at any time to optimize cash flow.
'David is a wonderful partner, he really is, but when you look at the sheer numbers, keeping him attached to my survivorship benefit is essentially equivalent to leasing a luxury SUV I am legally forbidden from driving,' Miller said, adjusting her glasses while scrolling through a Monte Carlo simulation that predicted her husband’s impending death would coincide nicely with a trip to Cabo. 'If I take the single-life payout, I can afford an ocean-view condo and maybe a small dog. If I add David to the policy, I’m basically paying a monthly tribute to a guy who leaves cabinet doors open and asks what’s for dinner while staring directly at a full refrigerator.'
According to retirement experts, the traditional pension system was cleverly designed around the romantic notion that people would want their loved ones to not starve to death in the event of their untimely demise. However, modern financial advisors are increasingly steering clients toward the far more pragmatic approach of viewing spouses and children as dead weight on a balance sheet.
'The mistake people make is viewing marriage through the lens of emotional commitment rather than portfolio drag,' said Certified Financial Planner Marcus Vance, noting that a surviving spouse is essentially an unfunded liability with human feelings. 'When you break down the numbers, every year David continues to draw oxygen after Brenda’s retirement is essentially capital siphoned away from a diversified portfolio of index funds and high-yield savings accounts. At 42, you have to ask yourself: Do I want to subsidize his hobbies, or do I want a robust emergency fund for a roof replacement in 2038?'
Miller noted that while the children are also technically eligible for beneficiary status, their inclusion carries an even steeper penalty due to their expected lifespan. Keeping both children on the plan until age 26 would require Miller to forfeit nearly half her monthly benefit, a price she described as economically irrational given their current academic performance and refusal to take out the trash without a formal grievance process.
'The kids are a high-risk, long-duration asset class with a notoriously poor track record of paying you back in your old age,' Miller said. 'If I drop them now, I can lock in a higher monthly annuity and leave them with the invaluable gift of early financial independence, which is a polite way of saying they’re going to need to figure out their own community college tuition.'
Financial analysts have praised the ruthless efficiency of Miller’s approach, pointing out that true retirement freedom requires a willingness to emotionally detach from anyone who might theoretically outlive you. Industry insiders suggest that future iterations of corporate pension plans will likely introduce dynamic pricing tiers, allowing workers to toggle their spouse’s survivorship status on and off via a mobile app depending on market volatility and the state of their marriage.
As the deadline to lock in her election approaches, Miller remains focused on the bottom line. She plans to sit down with David this weekend to discuss her findings, go over the actuarial tables, and gently explain that while she loves him dearly, she loves the idea of a fixed annuity without survivor benefits just a little bit more.