NEW YORK, NY – Major credit card issuers have confirmed they actively prefer applicants demonstrating a consistent, if precarious, reliance on revolving debt over wealthy retirees who simply draw from substantial IRAs. The revelation came after a recent inquiry from a financially solvent, retired individual who was denied a basic retail credit card despite possessing millions in assets, prompting outrage from absolutely no one in the financial sector.
“It’s not about how much money you *have*,” stated Brad “The Calculator” Thorne, Head of Consumer Debt Origination at Chase Bank, in an exclusive interview conducted via hologram. “It’s about how predictably we can extract revenue from you. Someone who dips into their IRA for a new roof or a European vacation? That’s too sporadic. Too responsible, frankly. Our algorithms are designed for the beautiful rhythm of monthly minimums, for the gentle hum of a carried balance and the sweet, sweet sound of compounding interest.”
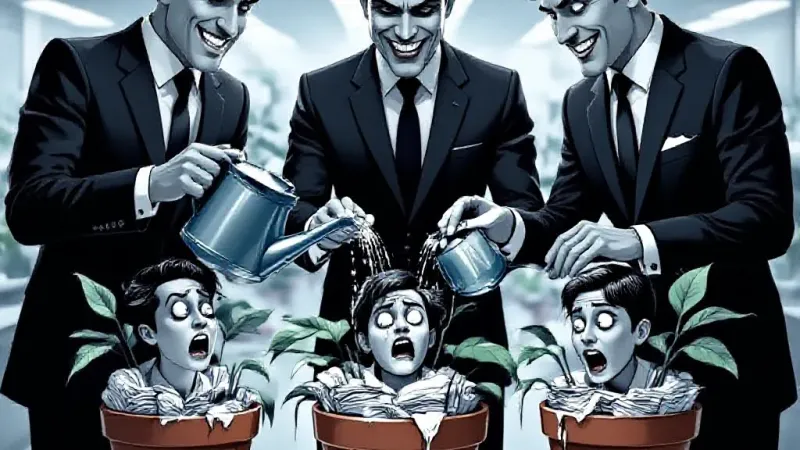
Thorne elaborated that the ideal customer profile involves a stable, but not overly abundant, W-2 income, coupled with a healthy propensity to occasionally forget a due date or make only the minimum payment. “Think of it as a finely tuned ecosystem,” Thorne explained, gesturing with a spreadsheet populated entirely by tiny, smiling dollar signs. “The consistent wage earner who occasionally flirts with financial precarity is our lifeblood. They’re predictable. They’re loyal to the cycle. The retiree with their 'nest egg' is too… free-range. We can't model that. There's no consistent yield for us if they just pay it off every month like some kind of financial anarchist.”
The wealthy retiree, identified only as "Harold R." of Boca Raton, expressed confusion. “I draw from my IRA as needed for household repairs, trips, and other larger expenses,” Harold told Hambry, clearly missing the point entirely. “It just doesn’t seem fair.” Financial institutions, however, counter that Harold’s stable wealth means he is less likely to incur interest charges, late fees, or become entangled in the lucrative web of debt consolidation offers. “He’s a ghost,” said a source within Wells Fargo’s AI-powered risk assessment unit, speaking on condition of anonymity. “He doesn't exist within our optimal profit pathways. He's practically anti-revenue.”
A leaked internal memo from Capital One’s "Project Perpetual Profit" further detailed how "diversified asset portfolios, while commendable for the individual, present an undesirable lack of urgency in repayment patterns." The memo praised "the burgeoning demographic of debt-optimized citizens" who, due to housing costs, student loans, and stagnant wages, are "perfectly primed for sustained, low-risk, high-interest engagement." The document concluded that "true financial stability, paradoxically, reduces a consumer's value proposition to the modern credit market, making them, quite frankly, a drag on quarterly earnings."
The banking sector confirmed that while cash is king for consumers, for lenders, the real crown jewels are consistent minimum payments on an ever-growing principal, ensuring the financial industry continues to thrive on the subtle dread of its most predictable customers.